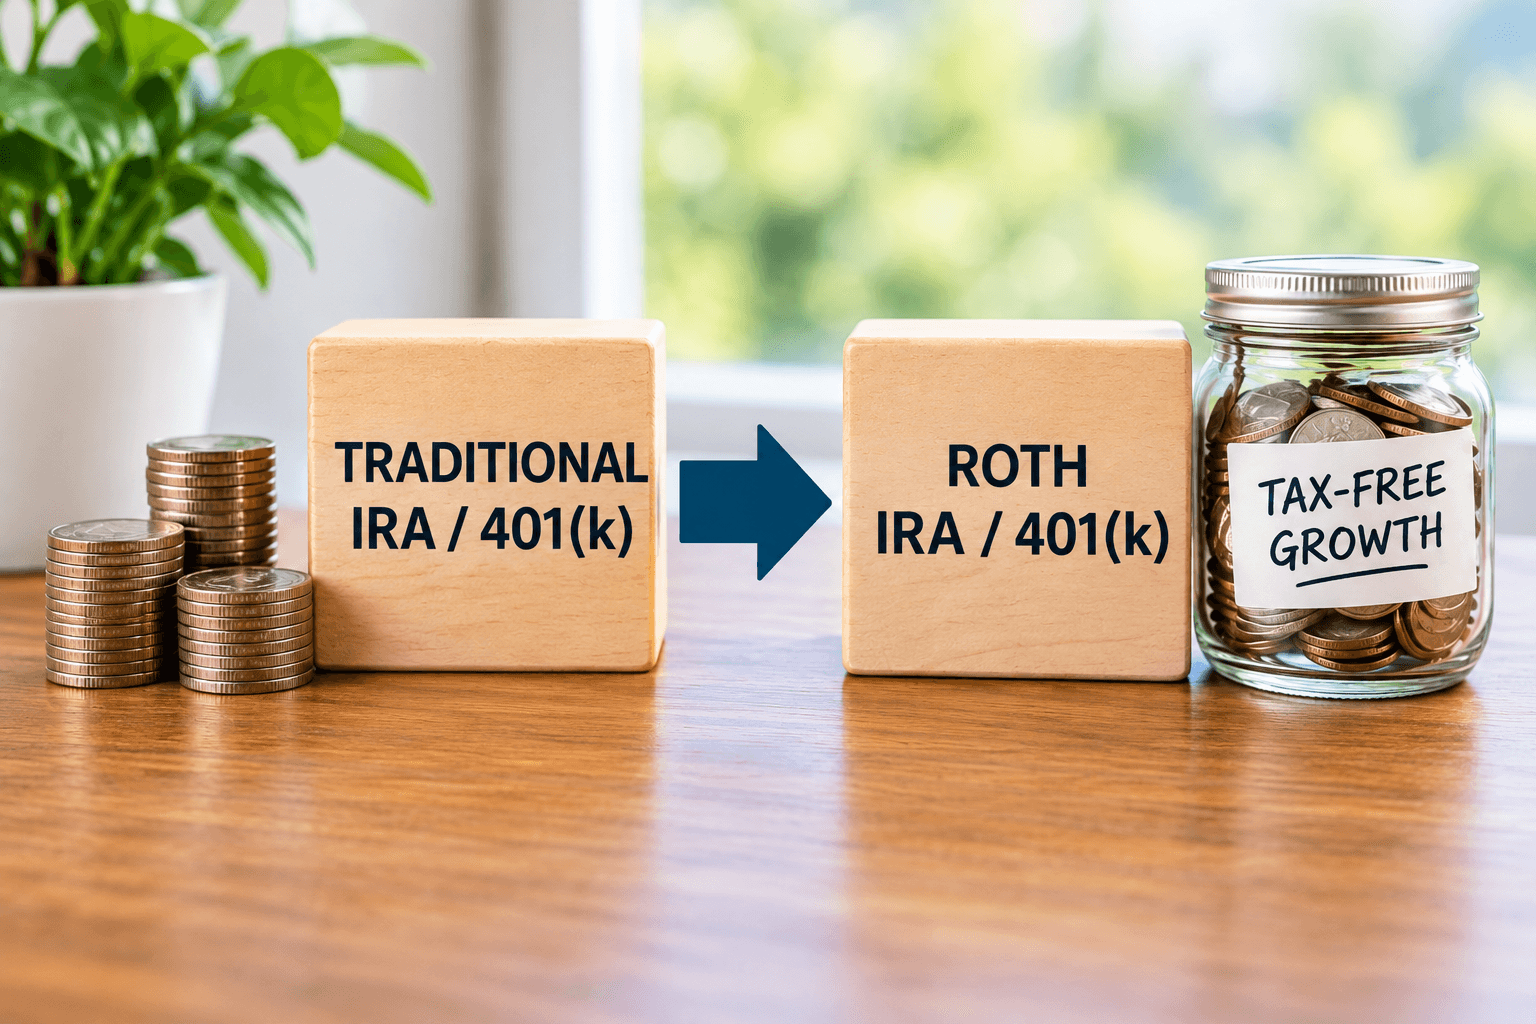
A Roth conversion moves pre-tax money from a traditional IRA or 401(k) into a Roth IRA or Roth account. The converted amount is generally added to federal taxable income that year, while Pennsylvania generally does not tax a full conversion. Whether it makes sense may depend on your tax bracket, Medicare premiums, timing, and how you pay the tax.
For households across Allentown, Bethlehem, and Easton, the question usually is not whether Roth accounts exist, but how money actually gets from a 401(k) or traditional IRA into one, and what that move may cost. This guide walks through the mechanics in plain terms, the tax items a conversion can touch, how Pennsylvania treats it, and the questions many households review before acting. Rules below were reviewed against IRS, Social Security Administration, and Pennsylvania sources as of October 16, 2026, and they can change.
Two Paths: Converting From an IRA or From a 401(k)
The mechanics differ depending on where the money starts. These are the three routes households most often ask about:
- Traditional IRA to Roth IRA. The IRS describes three ways to convert: a rollover (you receive a distribution and deposit it in a Roth IRA within 60 days), a trustee-to-trustee transfer to a Roth IRA at another institution, or a transfer between a traditional and a Roth IRA at the same institution. A conversion results in tax on any untaxed amounts in the traditional IRA and is reported on Form 8606 (IRS, as of October 16, 2026). The limitation is that the tax bill arrives for that tax year whether or not you need the money.
- 401(k) to Roth IRA. When you leave an employer, you may be able to roll a 401(k) balance to a Roth IRA. The IRS says a rollover is not taxable unless it goes to a Roth IRA or designated Roth account from another type of plan, so the untaxed portion is generally taxable in the year of the rollover (as of October 16, 2026). A direct rollover generally avoids the mandatory 20 percent withholding that applies when a plan pays the money to you first.
- In-plan Roth rollover. Some 401(k), 403(b), and governmental 457(b) plans allow you to move pre-tax balances into the plan's own Roth account. The IRS says you must include the previously untaxed amount in gross income in the year of the transfer, and that your plan may or may not allow it (as of October 16, 2026). This route keeps the money inside the employer plan, so the plan's investment menu, fees, and rules continue to apply.
For university faculty and hospital employees, plan terms can vary widely, so it is worth reading our guides on the difference between a 401(k) and a 403(b) and 401(a) and 401(k) plans, then confirming what your own plan documents allow.
What a Conversion Can Affect on Your Tax Return
The converted amount is generally added to your income for the year, as if it had been withdrawn (IRS Publication 590-A, as of October 16, 2026). That can ripple into several other items:
- Federal tax bracket. A large conversion could push part of your income into a higher bracket. Some households spread a conversion over several years to manage that, although spreading it out also means the plan stays exposed to future tax law changes.
- Medicare premium surcharges (IRMAA). The Social Security Administration generally uses modified adjusted gross income from two years before the premium year to set the income-related monthly adjustment amount (as of October 16, 2026). A conversion in one year could therefore show up in Medicare premiums two years later. SSA defines modified adjusted gross income as adjusted gross income plus tax-exempt interest.
- Social Security taxation. The IRS says benefits are not taxable unless modified adjusted gross income plus one half of your benefits exceeds the base amount for your filing status (as of October 16, 2026). Because a conversion raises adjusted gross income, it could cause more of a benefit to become taxable in that year.
- How the tax is paid. Paying the tax from money outside the account generally leaves more in the Roth, but not every household has that cash available. If tax is withheld from the converted amount, that portion is not converted, and if you are under age 59½ it may be subject to an additional 10 percent tax unless an exception applies (IRS, as of October 16, 2026).
Pennsylvania and Local Tax Treatment
Pennsylvania does not follow the federal rule here, which is why a national article may not match a Pennsylvania return. The Pennsylvania Department of Revenue's guidance on Roth IRAs (updated October 13, 2026, reviewed as of October 16, 2026) says the following in general terms:
- Traditional IRA to Roth IRA. A conversion is generally not subject to Pennsylvania personal income tax when it moves by trustee-to-trustee transfer or by rollover within 60 days.
- Amounts that do not reach the Roth IRA. Money taken from the traditional IRA but not deposited in the Roth IRA, including federal withholding, is subject to Pennsylvania tax, with basis allocated pro rata. A partial conversion also requires pro rata allocation of basis.
- Distributions from eligible plans. Distributions from eligible retirement plans received after reaching age 59½, or after retiring once the plan's age or service conditions are met, are generally not taxable for Pennsylvania personal income tax. The same page says a direct trustee-to-trustee transfer from a qualified plan to an IRA is not treated as taxable income, which appears to be the relevant rule for a 401(k) rolled directly to a Roth IRA, though a tax professional should confirm this for your situation.
Local earned income tax is a separate question. It is generally based on earned income, and the Pennsylvania Department of Community and Economic Development's local earned income tax return instructions (CLGS-32-1, 04/2024, reviewed as of October 16, 2026) state that some payments from IRAs and 401(k)s are not taxable, and direct readers to their local collector for questions. Because rules can differ by situation, such as a withdrawal taken early, check with your local tax collector or tax professional.
A Pennsylvania result that looks favorable does not remove the federal tax. The federal tax, Medicare, and Social Security items above still apply.
The Five-Year Rules
There are two separate five-year rules, and people often mix them up (IRS Publication 590-B, as of October 16, 2026):
- Qualified distribution rule. Earnings in a Roth IRA are generally tax-free only if five tax years have passed since the first tax year of a Roth IRA contribution (a conversion can start this period if it was your first), and you also meet a condition such as being age 59½ or older.
- Conversion rule. Each conversion has its own five-year period for purposes of the 10 percent additional tax on an early withdrawal of the taxable converted amount, starting January 1 of the conversion year. This generally matters if you are under age 59½.
For a retiree already past 59½, the conversion rule may matter less, but the qualified distribution rule can still affect when earnings come out tax-free. Which rule applies to a given withdrawal depends on your history of Roth contributions and conversions.
Timing Before RMDs Begin
Many pre-retirees and retirees look at the years after work ends and before required minimum distributions start as a possible window. Income in those years may be lower than it will be later, which could mean the converted amount is taxed at a lower rate. The trade-off is that conversions can compete with other income decisions in the same years, including Social Security claiming, which we discuss in our guide to Social Security claiming strategies.
RMD age depends on your birth year and is currently 73 or 75 (IRS, as of October 16, 2026). A required minimum distribution itself generally cannot be rolled over or converted (IRS, as of October 16, 2026). The IRS says Roth IRA owners can leave amounts in the account as long as they live, which is why some households consider conversions ahead of RMD age. Our guide to Roth conversions before RMDs begin covers that timing in more detail. Households with concentrated stock or large taxable gains may also want to read how a conversion year interacts with capital gains tax in retirement.
Questions to Ask Before Converting
These are conversation starters for a tax professional, not a recommendation to convert:
- How much would this conversion add to my taxable income, and which bracket would it reach?
- Can I pay the tax from money outside the retirement account?
- How could the added income affect Medicare premiums two years from now?
- How could it affect how much of my Social Security benefit is taxable?
- Does my plan allow in-plan Roth rollovers, or only a rollover to a Roth IRA?
- What are the five-year rules for my age and Roth history?
- Would converting in stages over several years change the picture?
- How does the account fit with my retirement income plan, my heirs, and other tax planning?
Where Conversions Fit in a Retirement Income Plan
A Roth conversion is one tool among many, and it is best reviewed as part of a broader plan rather than as a stand-alone decision. Our article on withdrawal order and retirement income planning explains how withdrawals, Social Security, and taxes interact, and our tax planning service page describes how we look at conversions alongside the rest of a household's tax picture. For workplace plans, see our overview of 401(k) and retirement plan management.
We work with pre-retirees, retirees, medical professionals, and higher-education faculty and administrators across Allentown, Bethlehem, Easton, and the broader Lehigh Valley. If you would like to talk through how a conversion could fit your own situation, you can schedule a conversation with our team.
Next step for households across the region
A conversion decision touches retirement income, taxes, and legacy goals at once. You may want to explore our income planning, tax planning, and estate and legacy planning services, or browse our helpful resources. Confirm tax treatment with a qualified tax professional before you convert any account.
Frequently Asked Questions
Can you convert your entire 401(k) to a Roth?
It may be possible, but it depends on your plan and the type of money in the account. Plans generally allow rollovers to a Roth IRA after certain events such as leaving the employer, and some plans allow in-plan Roth rollovers while you are still working. Pre-tax amounts moved to a Roth are generally added to taxable income that year, so a full conversion can create a large tax bill. Some households convert in stages instead. Plan terms vary, so confirm the details with your plan administrator.
Do I pay taxes if I roll over a 401(k) to a Roth IRA?
Generally, yes, on any previously untaxed amount. The IRS says a rollover to a Roth IRA from another type of plan is taxable, and the untaxed portion is included in income for the year of the rollover. A rollover from a pre-tax 401(k) to a traditional IRA is different, because it generally defers the tax. Pennsylvania treats a conversion differently from the federal government, as described above, so federal and state results may not match.
What are the disadvantages of a Roth conversion?
A conversion generally adds to taxable income in the year it happens, which could raise your tax bracket, make more Social Security benefits taxable, or increase Medicare premiums two years later. It generally cannot be undone once completed. The tax is often best paid from money outside the account, which not every household has available. Converted amounts may also be subject to a separate five-year rule if withdrawn before age 59½. Whether the trade-offs are acceptable depends on individual circumstances.
What is the biggest Roth conversion mistake?
There is no single answer, but a commonly discussed pitfall is converting without first estimating the full effect on the household's tax return, Medicare premiums, and Social Security taxation. Other pitfalls include paying the tax out of the converted amount, overlooking the five-year rules, or trying to convert a required minimum distribution, which generally cannot be converted. A tax professional can help review these items before any money moves.
Is there an income limit on Roth conversions?
The IRS income limits apply to Roth IRA contributions, not to conversions. A traditional IRA or eligible plan balance can generally be converted regardless of income, although the amount converted is generally taxable to the extent it has not already been taxed. High income in the conversion year can still affect other items, such as Medicare premiums, so the income level matters even though it does not block the conversion.
Does Pennsylvania tax Roth conversions?
According to the Pennsylvania Department of Revenue, a conversion of a traditional IRA to a Roth IRA is generally not subject to Pennsylvania personal income tax when the full amount is moved by a trustee-to-trustee transfer or a rollover within 60 days. Any amount withheld or otherwise not deposited into the Roth IRA may be taxable. The federal treatment is different, because a conversion is generally taxable for federal purposes. Confirm your own situation with a tax professional.
Can I undo a Roth conversion?
Generally, no. Under the Tax Cuts and Jobs Act, a conversion to a Roth IRA made on or after January 1, 2018 cannot be recharacterized as a contribution to a traditional IRA. This is one reason many households estimate the tax cost carefully before converting, and why a partial conversion may be easier to review than a single large one.
This article is for educational purposes only and is not tax, legal, or individualized investment advice. Tax rules change, and results depend on your individual circumstances. Consult a qualified tax professional before making a conversion decision.
Wealthcare of the Lehigh Valley