After losing a spouse, a few tasks are time-sensitive: making sure Social Security has been told, keeping insurance premiums paid, and locating key documents. Most larger decisions, including rollovers, claiming ages, and plan changes, can usually wait while you gather facts and ask questions. This guide separates what cannot wait from what may be allowed to wait.
Losing a spouse often means taking on financial decisions you have not made alone before. For widows, widowers, and other surviving spouses across Allentown, Bethlehem, and Easton, the hardest part can be knowing which choices are urgent. Many are not. This guide is educational and is not a recommendation, and the right answers depend on your accounts, your age, your household, and your plan documents.
Sources and as-of date: the benefit and tax rules summarized below come from the Social Security Administration (survivor benefits, who can get survivor benefits, what to do when someone dies), the IRS (Publication 501, Publication 559, Publication 590-B, Retirement topics: Beneficiary), and the Pennsylvania Department of Revenue, reviewed October 10, 2026. Rules and dollar amounts can change, so check each page for the current version.
What cannot wait: the first days and weeks
A short list of tasks tends to carry real consequences if delayed. None of them requires you to make a long-term financial decision.
- Order several certified death certificates. Banks, insurers, plan administrators, and government agencies commonly ask for them. Your funeral director can usually tell you how many copies households tend to need.
- Confirm Social Security has been notified. SSA says funeral homes generally report a death, so you typically do not need to. If no funeral home is involved, or you are unsure it was reported, SSA asks you to call 1-800-772-1213 with the name, Social Security number, date of birth, and date of death of the person who died. A spouse might also qualify for a one-time $255 lump-sum death payment, according to SSA. Applying for survivor benefits is a separate step, covered below.
- Keep premiums and essential bills current. Check that homeowners, auto, health, and life or long-term care insurance premiums, the mortgage or rent, and utilities keep being paid. A lapse in coverage can be hard to reverse. If your health coverage came through your spouse's employer, ask the benefits office what options exist for you and how quickly you need to respond.
- Locate the key documents. Gather the will and any trust, powers of attorney, recent account statements, insurance policies, deeds and vehicle titles, tax returns, and any list of passwords or account numbers. Our guide to estate and legacy planning explains why beneficiary forms and account titling matter as much as the will.
- Contact an estate attorney. In Pennsylvania, estates are generally opened through the county Register of Wills, and an attorney can explain what applies to your situation, including who needs to be named and what must be filed.
What can usually wait
It is common to feel pressure to act quickly. Many financial decisions are better made after the first few months, once you have a full picture and some distance from the loss. These are often reasonable to postpone, subject to any dates your plan, your tax professional, or the IRS identifies:
- Moving or consolidating investment accounts
- Deciding when to claim a survivor benefit or your own retirement benefit
- Selling a home or making large gifts
- Making major purchases or lending money to family
- Changing your investment approach or hiring a new advisor in a hurry
If someone urges you to move money or buy a product right away, that is a reason to slow down, not speed up. You can ask for time in writing, and a trusted attorney, tax professional, or planner can review any proposal with you.
The first 90 days: accounts, beneficiaries, and retitling
Once the urgent items are handled, the next stage is organizing and understanding what you have. This is a fact-gathering phase, not a decision-making phase.
- Build one list of everything. Include bank, brokerage, retirement, and pension accounts, life insurance and annuities, real estate, vehicles, debts, and automatic payments. Note who is listed as owner and as beneficiary on each.
- Identify how each account passes. Joint accounts, accounts with a named beneficiary, and accounts titled in an individual name or a trust can each be handled differently. An attorney can confirm the result for each one.
- Notify institutions and request the next steps in writing. Ask each custodian, insurer, and plan administrator what they need to retitle an account or pay a claim. Keep copies of everything you send.
- Review your own beneficiary designations. Your spouse may have been your primary beneficiary on your own accounts. Update those forms so they reflect your current wishes.
- Reset your monthly cash flow. Compare what is coming in (Social Security, pensions, any survivor annuity, work income) with what is going out. A clear picture helps you avoid pulling more from savings than you intended.
- Look at insurance and credit. Review your own coverage, and ask whether any joint credit cards or accounts should be retitled in your name.
Survivor Social Security: what to know before choosing a date
Social Security rules for survivors are different from the rules for retirement benefits, and the details of your claim depend on both spouses' records. According to SSA (who can get survivor benefits), a surviving spouse may be eligible if they:
- Are age 60 or older, or age 50 to 59 with a disability, and
- Were married at least 9 months before the death, and
- Did not remarry before age 60 (age 50 if disabled).
Some people may qualify regardless of age or length of marriage, for example when caring for a child of the person who died.
The amount depends on when you claim. SSA says survivor payments start at 71.5% of the deceased spouse's benefit and increase the longer you wait, up to 100% at your full retirement age for survivor benefits, which falls between 66 and 67 (SSA, what you could get). Claiming earlier means a smaller monthly amount, and waiting means going without the payment in the meantime, so each choice has a cost.
The benefits are not added together, but you may be able to switch. SSA says that if you are eligible for a survivor benefit and another benefit, you choose which payment to receive, and you can switch later. For example, you could start with a survivor benefit and change to your own retirement benefit at age 70 when that payment is highest. The right order depends on both work records, so ask SSA for a record-specific estimate before deciding.
Working may reduce payments for a time. SSA notes that survivor benefits may have earnings limits depending on your age, and payments could be temporarily reduced if you earn above the limit.
For a broader look at the claiming decision, including how spousal and survivor benefits differ and how the higher earner's choice may affect income after one spouse dies, read our guide to Social Security claiming strategies. Our overview of Social Security at 62 vs. 67 vs. 70 explains how starting ages affect a worker's own benefit.
Your spouse's IRA or workplace plan: rollover choices and trade-offs
Retirement accounts often hold a large share of a household's savings, and the choices a surviving spouse faces can be more flexible than those of other heirs. That flexibility also makes it worth slowing down. The sections below describe general trade-offs, not a recommendation about any account.
If the account is an IRA. Per IRS Publication 590-B, a surviving spouse who inherits a traditional IRA generally has two broad paths:
- Treat it as your own. You can designate yourself as owner or roll it over into your own IRA. The account is then generally treated like any other IRA of yours, which means withdrawals before age 59½ may be subject to the 10% additional tax unless an exception applies, and required distributions follow the rules for your own age. This path may offer simplicity and flexibility, but the early-withdrawal rule could matter if you are younger than 59½ and need to draw on the money.
- Keep it as an inherited IRA. Distributions from an inherited IRA are generally not subject to the 10% additional tax on early withdrawals, even if you are under 59½. Beneficiary distribution rules apply instead, and their timing depends on factors such as your spouse's age and whether they had begun required distributions (IRS, Retirement topics: Beneficiary). This path may help with access to funds before 59½, but it can come with required distributions that you would not face otherwise.
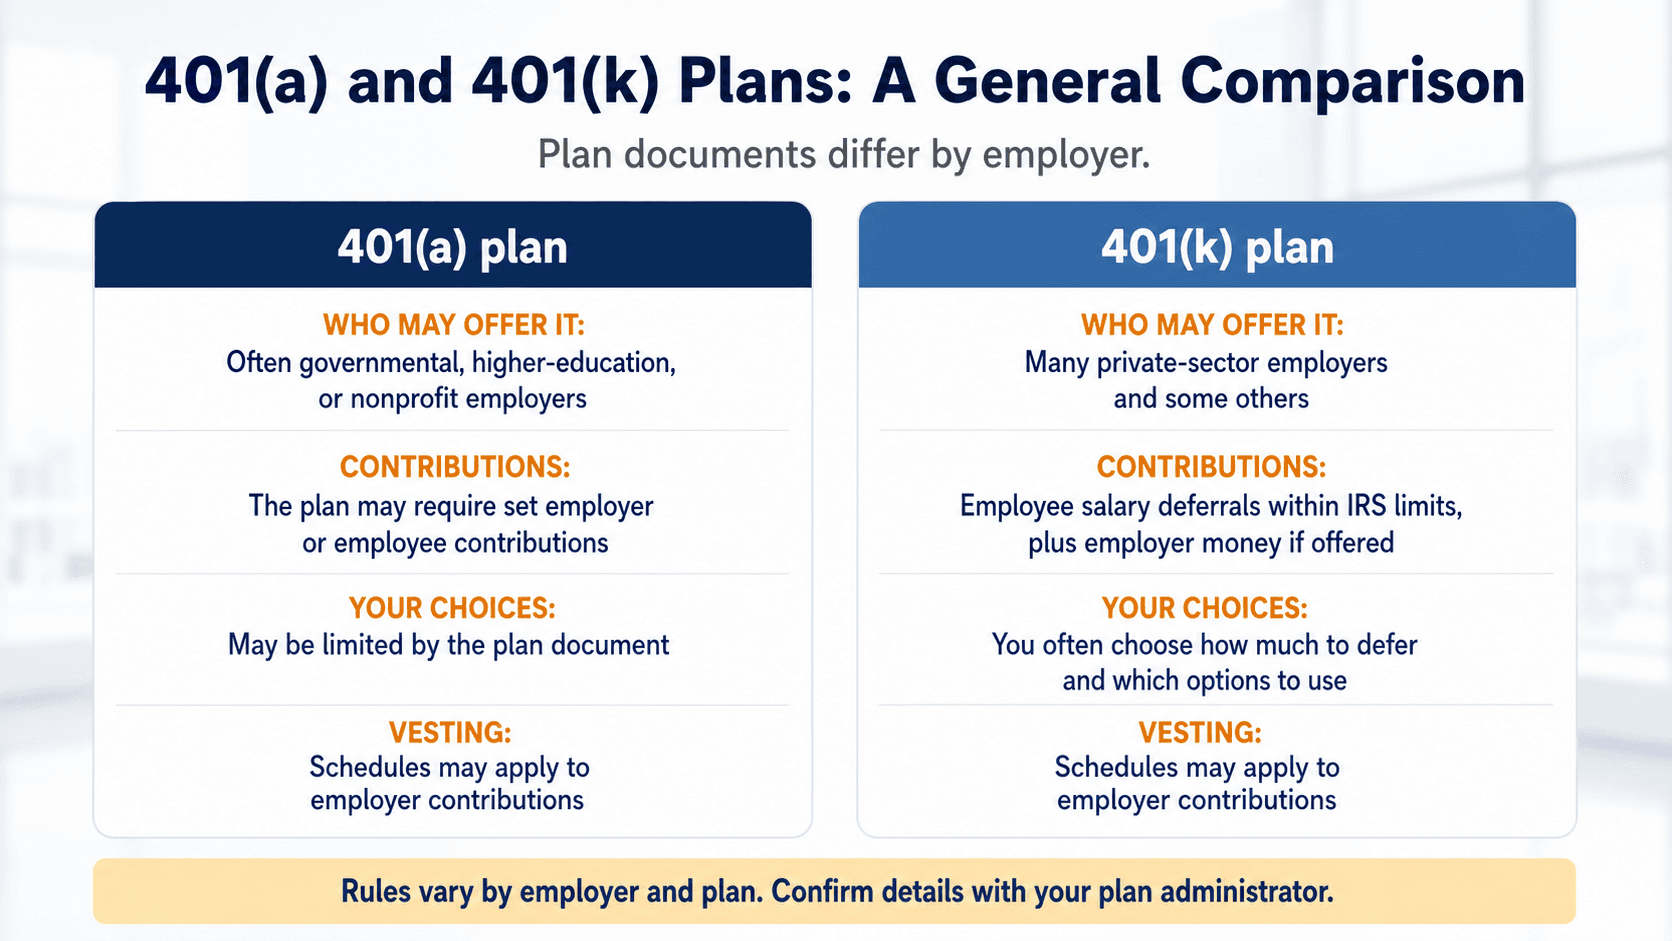
If the account is a 401(k), 403(b), or other workplace plan. The plan document sets the distribution options, and the IRS notes that a spouse may have more options within a plan than a non-spouse beneficiary. Contact the plan administrator for the options available. Our article on managing your retirement plan outlines the general choices when a plan balance moves.
Points that apply either way.
- A required distribution for the year of death may still be due. The IRS says that for the year of the account owner's death, the required distribution is any amount the owner had to take and had not yet taken. A required distribution generally cannot be rolled over.
- Some elections have dates. The IRS says whether a spouse is the sole beneficiary is determined by September 30 of the year after the year of death, which is one reason to confirm timelines with the custodian and a tax professional.
- Roth and pre-tax balances differ. Withdrawals of pre-tax money are generally taxable income, while inherited Roth accounts follow their own rules.
- Some decisions are hard to reverse. Once funds are moved or elections are made, it may not be possible to undo the choice. Taking a few months to compare options with a tax professional is often reasonable.
How your tax filing status may change
Filing status affects tax brackets and the standard deduction, so it is worth planning for early. The IRS describes the general pattern in Publication 501 and Publication 559:
- Year of death. If you did not remarry before the end of that year, you may be able to file a joint return with your deceased spouse. That is generally the last year a joint return with that spouse is available.
- The next two years. You may qualify to file as a qualifying surviving spouse if you meet the IRS tests, which include having a child or stepchild who qualifies as your dependent, living in your home all year, and paying more than half the cost of keeping up the home. This status uses joint-return rates and the joint standard deduction.
- After that, or if you do not qualify. Single or head of household status may apply, depending on your situation. Moving to a single filing status can change your tax bracket and how much of your Social Security is taxable, so it can affect your income plan.
A tax professional can confirm which status applies to you, and who needs to sign the final return for your spouse.
Updating your income plan and estate plan
After the first few months, the longer-term work is to rebuild a plan for one household instead of two.
- Income plan. Look at the sources of income you can count on, the expenses that continue, and the savings you may draw from. Our guide to retirement income planning describes the questions involved, and our income planning service looks at how the pieces fit together, subject to your circumstances.
- Estate documents. Wills, powers of attorney, healthcare directives, and trusts often name a spouse in key roles. An estate attorney can update them, and our estate and legacy planning service coordinates beneficiary designations and account titling with those documents.
- Pennsylvania inheritance tax. The Pennsylvania Department of Revenue lists a 0% inheritance tax rate on transfers to a surviving spouse, though an inheritance tax return may still need to be filed even when no tax is due (PA Department of Revenue). Rates differ for other heirs, so your attorney can confirm how this applies.
- Tax planning. A change in filing status, income, and account types may affect your taxes for years. Coordinating withdrawals with your tax picture is part of the plan, and our overview of tax planning benefits explains why.
Questions to bring to your professionals
Consider bringing these to an attorney, a tax professional, and a planner when you are ready:
- Which accounts pass by beneficiary designation, which by title, and which through the estate?
- Which deadlines are real, and which are only pressure?
- For my IRA or plan options, what would I gain and give up by treating an account as my own versus keeping it as inherited?
- What survivor benefit does SSA estimate for me at different ages, and how does that compare with my own benefit?
- Which filing status may apply for this year and the next two?
- How much monthly income do I need, and where would it come from?
- Which beneficiary designations and legal documents of my own need to change?
Talk through your own situation
You do not have to sort this out alone or all at once. If you are a surviving spouse in the Lehigh Valley, a conversation can help you organize what you have, identify the dates that matter, and set aside the decisions that can wait. You can read more about the households we work with on our who we help page, or reach out through our contact page to start at your own pace. Any outcome depends on your circumstances, and you should confirm legal questions with an attorney and tax treatment with a tax professional.
Frequently Asked Questions
Can I keep my spouse's Social Security?
You may be eligible for a survivor benefit based on your spouse's work record, but it is not the same as keeping their payment. SSA says survivor benefits can start as early as age 60 for eligible spouses, and the amount depends on the work record and the age you claim. Confirm your eligibility and estimate directly with SSA.
Can I get both a survivor benefit and my own retirement benefit?
SSA says that if you are eligible for a survivor benefit and another benefit, you choose which payment to receive, and the payments are not added together. You may also be able to switch later. Ask SSA how this applies to your records.
Should I roll over my spouse's IRA into my own?
It depends on your age, your income needs, and the type of account. The IRS describes two general paths for a surviving spouse who is the sole beneficiary: treat the IRA as your own, or keep it as an inherited IRA, as outlined in Publication 590-B. Each has different rules for withdrawals before age 59½ and for required distributions, so compare them with a tax professional before moving any money.
What happens to my tax filing status after my spouse dies?
The IRS generally allows a surviving spouse who has not remarried to file a joint return with the deceased spouse for the year of death. For the next two years, you may qualify for qualifying surviving spouse status if you have a dependent child and meet the other tests in Publication 501. Otherwise, single or head of household status may apply, depending on your circumstances.
How long do I have to make big financial decisions?
Many major decisions, such as when to claim a survivor benefit or whether to retitle accounts, have no immediate deadline, and it is often reasonable to take time. A few items do have dates, including tax filings, any required minimum distribution still due for the year of death, and certain beneficiary elections. A planner, attorney, and tax professional can help you list the real deadlines.
This article is for general educational purposes and is not individualized tax, legal, or investment advice. Tax rules and plan terms vary, so consult a qualified professional about your situation.
Wealthcare of the Lehigh Valley